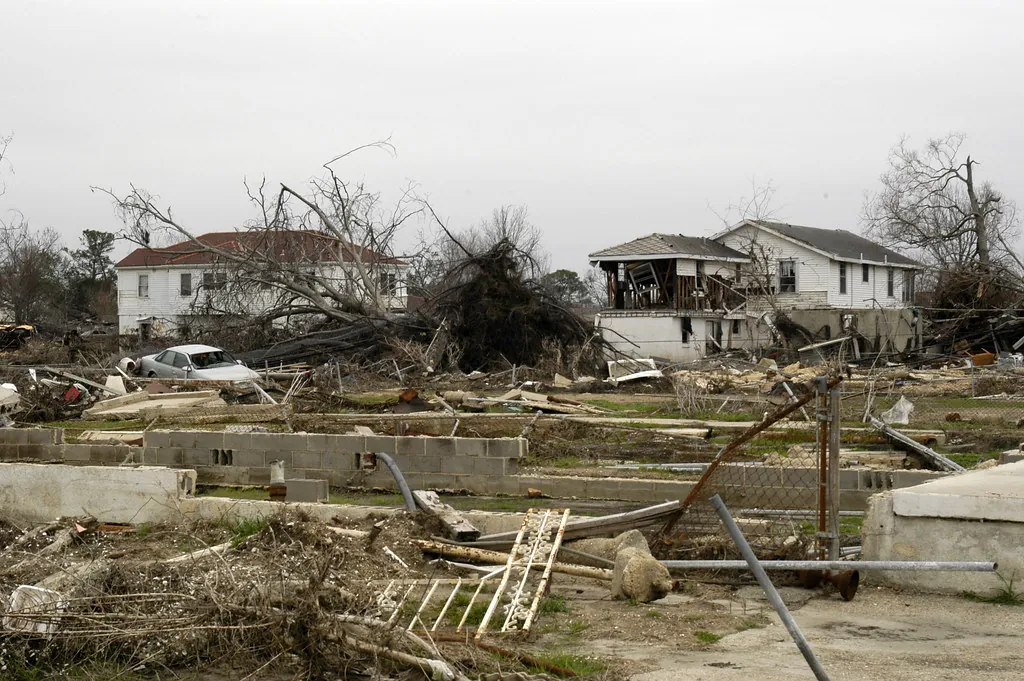
Tornado and wind damage appraisal in Wisconsin covers losses from twisters, derechos, downbursts and ordinary but violent straight-line gusts. When you and your insurer agree the wind damage is covered but disagree on what it costs to repair, we step in as your appraiser and build an independent valuation.
Wisconsin’s wind history
The state has a long record of destructive wind. The Barneveld tornado in June 1984 and the Oakfield tornado in July 1996 were both rated F5. The August 18, 2005 outbreak tore through the Stoughton area, and a tornado struck La Crosse in May 2011. In July 2019, derecho winds and downbursts flattened forests and damaged buildings across northern Wisconsin. Most claims, though, come from storms that never make headlines: a line of thunderstorms that peels back shingles in one subdivision and drops an oak through a garage in the next.
What wind estimates tend to miss
Damage you can’t see from the ground
Wind lifts shingles and breaks the seal strip even when the shingle settles back into place. Unsealed shingles are prone to blowing off in the next storm. Hand-lifting tabs and documenting creases is tedious work, and it is often skipped.
Structural movement
Strong gusts can rack walls, shift trusses and loosen connections. Cracked drywall seams, doors that suddenly stick and gaps at the sill plate can all point to framing movement that deserves an engineer’s look.
Tree and debris damage
A fallen tree may damage a roof, gutters, a deck and a fence all at once. Policies often limit debris removal and tree costs separately, so the estimate needs to separate those items cleanly.
Interior water
Once wind opens the envelope, rain follows. Wet insulation, ceiling stains and swollen subfloor are part of the same loss and should be scoped with it.
How we document a wind loss
- We inspect every elevation and roof slope, including shingle seal testing where lifting is suspected.
- We trace the direction of the storm from the damage pattern and note it in the file.
- We recommend a structural engineer where framing movement is possible and incorporate the findings.
- We separate dwelling, other structures, debris removal and contents so policy sublimits are applied correctly.
Farms and rural properties
Wind hits rural Wisconsin hard: machine sheds lose roof panels, barns lose siding and silos topple. If your loss is on a farm policy, our farm and barn appraisal page explains how those claims differ.
Need to understand what comes after the demand? Read the appraisal process guide, or browse answers in our appraisal FAQ. Owners around La Crosse and Wausau can find local details on our city pages.
Common questions
Is a derecho treated differently from a tornado in my policy?
Most homeowners and commercial policies cover windstorm generally without distinguishing tornado from straight-line wind. A separate wind or hail deductible may still apply.
The insurer says my shingles were already failing. What now?
That is partly a causation question. Independent documentation of seal failure and storm direction helps, but if coverage is being denied, talk with a Wisconsin attorney.
Are fallen trees covered?
Policies typically cover tree damage to insured structures and may pay limited amounts for tree removal. Check your policy’s debris removal and trees provisions for specific limits.