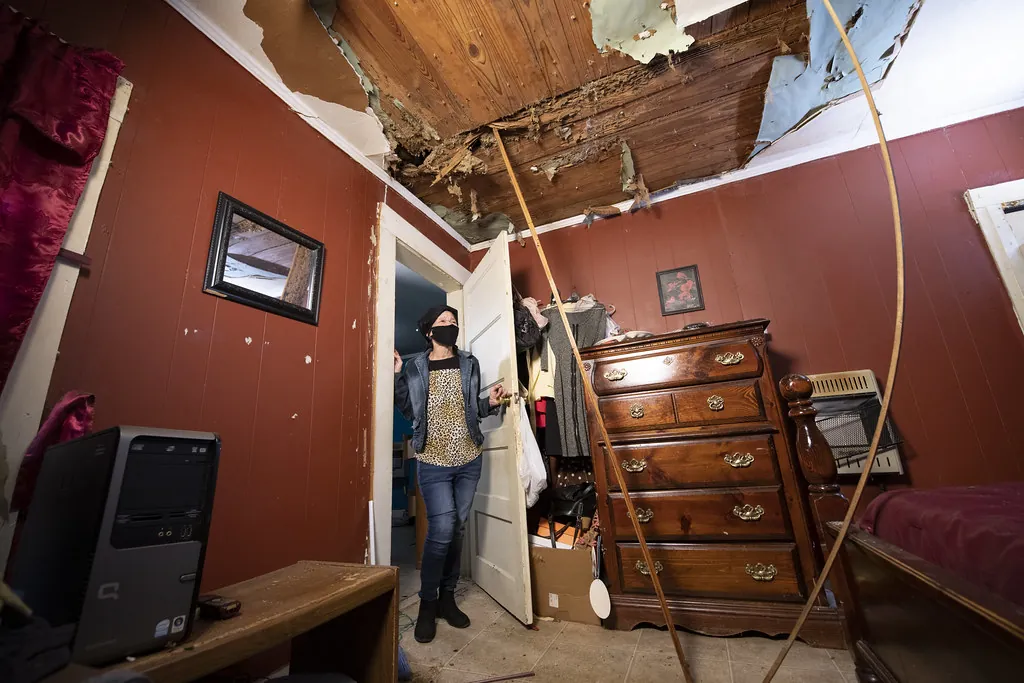
Water and sewer backup appraisal in Wisconsin is for owners whose claim involves sudden water damage, a burst pipe or supply line, or water and sewage backing up through drains. When the loss is covered but the dollar figure is disputed, we act as your appraiser and price the mitigation and rebuild in detail.
Three kinds of water, three sets of rules
Sudden and accidental discharge
A washing machine hose bursts, a water heater fails or a supply line splits. Most homeowners policies cover the resulting damage, subject to exclusions for long-term seepage and wear.
Sewer and drain backup
Standard policies typically exclude water that backs up through sewers or drains. Coverage usually comes from an endorsement, often with a limit such as a few thousand dollars up to a higher amount you chose when buying the policy. Some endorsements also cover sump pump failure. The limit matters as much as the scope, because an award can’t exceed the coverage available.
Flood
Surface water and overflowing rivers or lakes are excluded from standard property policies. Flood coverage is generally a separate policy, often through the National Flood Insurance Program, with its own claim process. We focus on water losses under your property policy.
When heavy rain overwhelms the system
Wisconsin has seen several rain events that sent water into thousands of basements: the July 2010 Milwaukee flash flooding, the June 2008 floods that drained Lake Delton and swamped the Baraboo and Portage area, and the August 2018 Dane County flash flood west of Madison. In events like these, the line between sewer backup and surface flooding can blur. How water entered the building drives which coverage applies.
What we look at on a water claim
- Mitigation. Extraction, drying equipment, antimicrobial treatment and daily monitoring logs. These charges are often cut on review.
- Category of water. Clean supply water, gray water and sewage call for very different protocols. Sewage-contaminated drywall, carpet and insulation generally have to be removed, not dried.
- Flood cuts and finishes. How high walls must be cut, whether cabinetry and flooring can be saved, and how much paint is needed for a uniform finish.
- Contents. Furniture, appliances, stored items and mechanicals in the basement.
- Limits and sublimits. We track how much of each coverage bucket the loss consumes.
Is appraisal right for a backup claim?
If the endorsement limit is low and the insurer has already paid it, appraisal won’t create more coverage. If the insurer paid well under the limit, or the claim involves sudden discharge under the main dwelling coverage, appraisal can be worthwhile. Our claim calculators can help you size the gap, and our carrier estimate review can tell you whether the mitigation line items look short.
Frozen pipes are their own winter story; see our ice dam and frozen pipe page. Milwaukee-area owners can visit our Milwaukee or Waukesha pages.
Common questions
Is sewer backup covered by my homeowners policy?
Usually only if you added a water or sewer backup endorsement. Check your declarations page for the endorsement and its limit.
Can appraisal increase my backup endorsement limit?
No. Appraisal sets the amount of loss, but the insurer’s payment is still capped by the limit you purchased.
Water came in through my basement walls during a storm. Is that backup or flood?
It depends on how the water entered. Water through drains is typically backup, while surface water through walls or windows is often treated as flood, which most property policies exclude.